Advanced mortgage strategies from a twenty-year strategist. Written to help you pay off sooner, save more, and retire three to four times wealthier — without paying more each month.
Manulife One at 4.95% vs. Five-Year Fixed at 3.94%: The Shrinking Cash Flow Advantage
Rebecca, a staff sergeant in Barrie, brings home $8,400 every two weeks after tax and pension contributions. Her spouse runs a small consulting practice that clears about $4,200 a month. They bought their house in 2022 with a five-year fixed mortgage at 5.1% on a $485,000 balance. That term expires in three months. The best five-year fixed rate their broker found is 3.94%. Manulife One is offering 4.95%, tied to Prime plus 0.50%. The difference is 101 basis points.
Most advice stops at the rate. The actual question is what happens to the $12,000 they keep in a chequing account for emergencies, the $3,800 that arrives from her biweekly pay, sits idle for six days, then goes to bills, and the $1,900 lump sum she gets twice a year from overtime settlements.
The Daily Balance Arithmetic
Under a traditional five-year fixed at 3.94%, that $12,000 emergency fund sits in a high-yield savings account earning maybe 2.8%, taxable. Over five years, it throws off roughly $1,680 in interest, taxed at her marginal rate of 43.4% (Ontario, $125,000 combined bracket). After tax: $793. The mortgage balance declines on its standard amortization schedule, costing about $101,700 in total interest over the five years at 3.94% on a 23-year remaining amortization.
Under Manulife One at 4.95%, the $12,000 emergency fund sits inside the mortgage account, reducing the principal by $12,000 every single day. The interest saved is not income, it's an expense reduction, so it's tax-free. At 4.95%, $12,000 working against the mortgage saves roughly $594 per year, or $2,970 over five years. Her biweekly pay arrives, sits in the account for six days on average before being spent, and during those six days it's reducing the balance and cutting interest charges. The two annual overtime lump sums of $1,900 each work the same way: instant reduction, zero lag.
Run the full scenario with realistic cash velocity, paycheques deposited, bills paid 5-7 days later, emergency fund parked inside the mortgage, and two annual $1,900 lump sums dropped in and left, and the total interest cost over five years on Manulife One comes in around $102,600. The five-year fixed costs $101,700. The difference is $900 over five years, or $15 a month, in favour of the fixed.
That's the break-even case where the offset loses narrowly. Change one variable and it flips.
Where the Offset Wins
If Rebecca's overtime settlements increase to $3,500 twice a year instead of $1,900, the Manulife One interest cost drops to roughly $98,900 over five years. The five-year fixed stays at $101,700 because lump-sum prepayments on a traditional mortgage are capped at 15-20% annually and often require manual coordination. The fixed mortgage wins by $2,800.
If the couple keeps $18,000 in the account instead of $12,000, perhaps they're risk-averse or planning a renovation in year three, the Manulife One interest saved jumps to about $4,400 over five years. The fixed mortgage still costs $101,700. The offset now wins by roughly $1,700, at the 101-basis-point rate premium.
The boundary case: the offset pays for itself when your average daily balance inside the account exceeds about 8-10% of your mortgage principal, or when you receive irregular lump-sum income more than once a year that you can park immediately without friction.
The Hidden Cost Nobody Prices
The $14 monthly administration fee on Manulife One adds $840 over five years. Traditional mortgages carry no equivalent fee. Include that and the break-even threshold moves: you need closer to $15,000 average daily float, not $12,000, to cover both the rate spread and the fee.
For dual-income households where one partner works in public safety, police, fire, paramedic, the product architecture matches the income pattern. Overtime is unpredictable. Shift differentials land irregularly. Court pay arrives in lump sums. A traditional mortgage requires manual prepayment coordination; the offset is automatic. The rate premium is the price of eliminating friction.
For households with stable, predictable paycheques and minimal float, the five-year fixed at 3.94% wins every time. The 4.95% rate is an expensive feature you're not using.

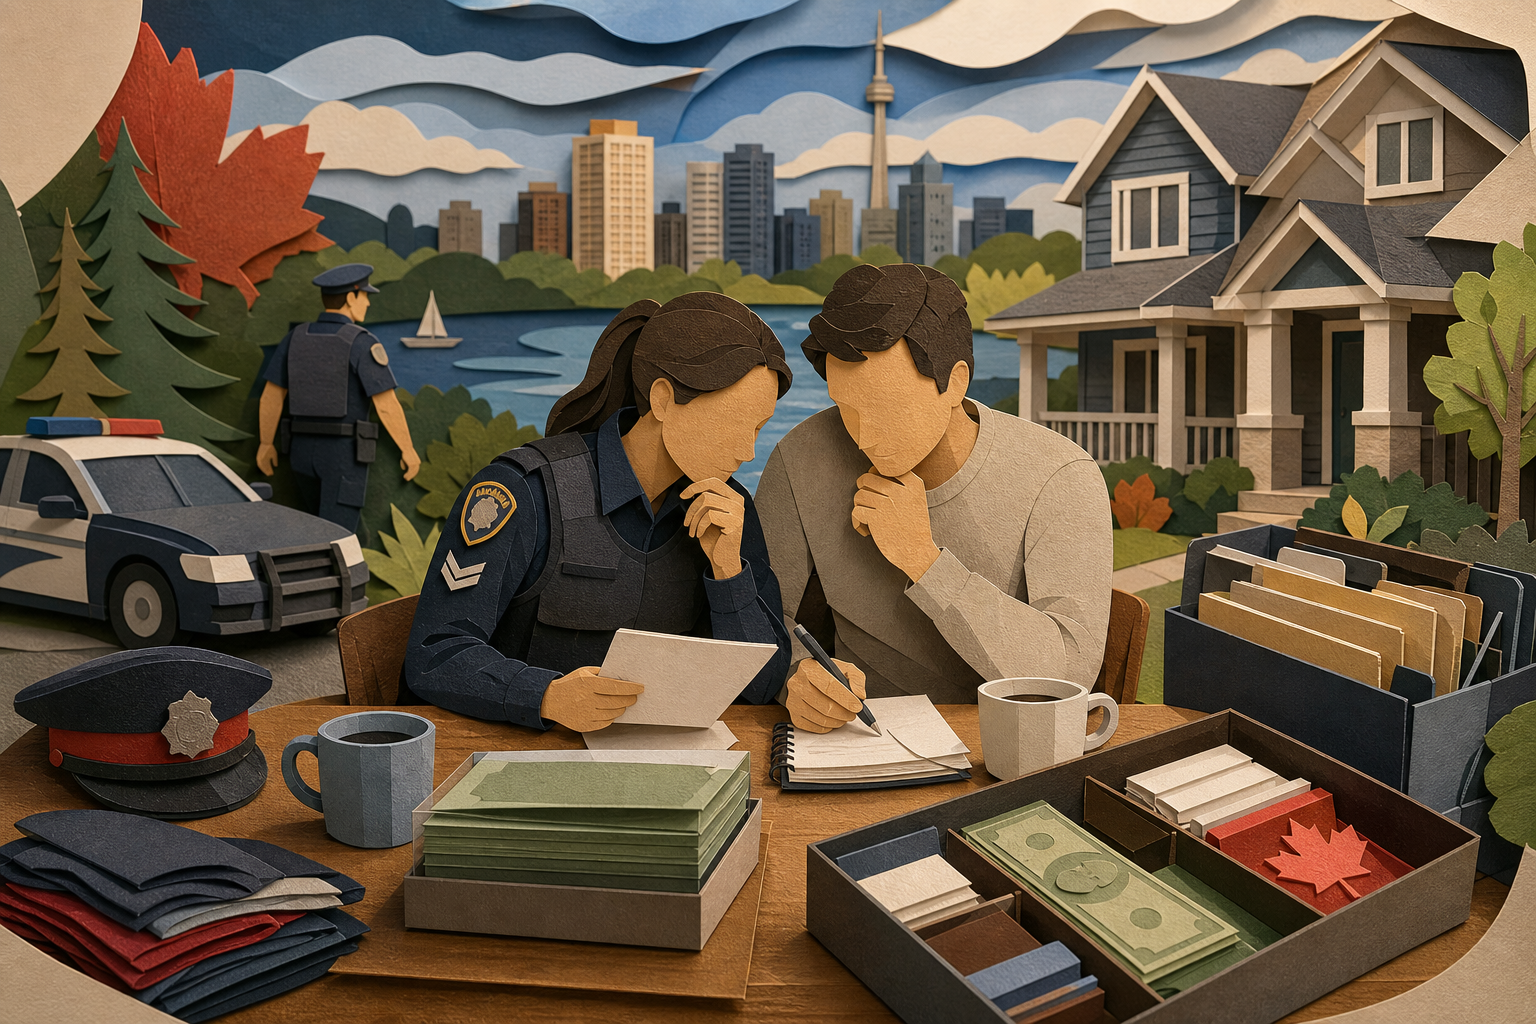

Rebecca, a staff sergeant in Barrie, brings home $8,400 every two weeks after tax and pension contributions. Her spouse runs a small consulting practice that clears about $4,200 a month. They bought their house in 2022 with a five-year fixed mortgage at 5.1% on a $485,000 balance. That term expires in three months. The best five-year fixed rate their broker found is 3.94%. Manulife One is offering 4.95%, tied to Prime plus 0.50%. The difference is 101 basis points.
Most advice stops at the rate. The actual question is what happens to the $12,000 they keep in a chequing account for emergencies, the $3,800 that arrives from her biweekly pay, sits idle for six days, then goes to bills, and the $1,900 lump sum she gets twice a year from overtime settlements.
The Daily Balance Arithmetic
Under a traditional five-year fixed at 3.94%, that $12,000 emergency fund sits in a high-yield savings account earning maybe 2.8%, taxable. Over five years, it throws off roughly $1,680 in interest, taxed at her marginal rate of 43.4% (Ontario, $125,000 combined bracket). After tax: $793. The mortgage balance declines on its standard amortization schedule, costing about $101,700 in total interest over the five years at 3.94% on a 23-year remaining amortization.
Under Manulife One at 4.95%, the $12,000 emergency fund sits inside the mortgage account, reducing the principal by $12,000 every single day. The interest saved is not income, it's an expense reduction, so it's tax-free. At 4.95%, $12,000 working against the mortgage saves roughly $594 per year, or $2,970 over five years. Her biweekly pay arrives, sits in the account for six days on average before being spent, and during those six days it's reducing the balance and cutting interest charges. The two annual overtime lump sums of $1,900 each work the same way: instant reduction, zero lag.
Run the full scenario with realistic cash velocity, paycheques deposited, bills paid 5-7 days later, emergency fund parked inside the mortgage, and two annual $1,900 lump sums dropped in and left, and the total interest cost over five years on Manulife One comes in around $102,600. The five-year fixed costs $101,700. The difference is $900 over five years, or $15 a month, in favour of the fixed.
That's the break-even case where the offset loses narrowly. Change one variable and it flips.
Where the Offset Wins
If Rebecca's overtime settlements increase to $3,500 twice a year instead of $1,900, the Manulife One interest cost drops to roughly $98,900 over five years. The five-year fixed stays at $101,700 because lump-sum prepayments on a traditional mortgage are capped at 15-20% annually and often require manual coordination. The fixed mortgage wins by $2,800.
If the couple keeps $18,000 in the account instead of $12,000, perhaps they're risk-averse or planning a renovation in year three, the Manulife One interest saved jumps to about $4,400 over five years. The fixed mortgage still costs $101,700. The offset now wins by roughly $1,700, at the 101-basis-point rate premium.
The boundary case: the offset pays for itself when your average daily balance inside the account exceeds about 8-10% of your mortgage principal, or when you receive irregular lump-sum income more than once a year that you can park immediately without friction.
The Hidden Cost Nobody Prices
The $14 monthly administration fee on Manulife One adds $840 over five years. Traditional mortgages carry no equivalent fee. Include that and the break-even threshold moves: you need closer to $15,000 average daily float, not $12,000, to cover both the rate spread and the fee.
For dual-income households where one partner works in public safety, police, fire, paramedic, the product architecture matches the income pattern. Overtime is unpredictable. Shift differentials land irregularly. Court pay arrives in lump sums. A traditional mortgage requires manual prepayment coordination; the offset is automatic. The rate premium is the price of eliminating friction.
For households with stable, predictable paycheques and minimal float, the five-year fixed at 3.94% wins every time. The 4.95% rate is an expensive feature you're not using.
Sources
Read Next
Canada's Big Six banks hit $37.5 billion in impaired loans, triple pre-pandemic levels
Your 2.5% Mortgage Rate and Ontario Divorce: 7 Ways to Keep or Share It
Fixed Mortgage Rates Climb as Bond Yields Erase Discount Room
You're Retiring in 2026 With a Mortgage Still Outstanding: The Four Restructuring Paths and How to Choose the Right One